Introduction
Dear Reader,
so far this year, 6,768 resale apartments and 833 new developments have been notarised in Berlin. In 2025 the figures were 12,514 and 1,428.
Resale apartments are notarised at an average of €5,230 per sqm. Year on year, the change is -1.0 %. New developments stand at €8,440 per sqm, with a year-on-year change of 3.0 %.
On the supply side, 37,107 resale listings are recorded. For 2025 the series shows 28,928 listings. The gap between asking price and transaction price is 8 %.

Resale market
Resale apartments in Berlin are notarised at an average of €5,230 per sqm. Year on year, the change is -€60 per sqm or -1.0 %.
| Period | Avg. sale price per sqm Change vs. prev. year in % |
|---|---|
| 2012 | 10.0 % |
| 2013 | 11.0 % |
| 2014 | 9.0 % |
| 2015 | 13.0 % |
| 2016 | 13.0 % |
| 2017 | 14.0 % |
| 2018 | 14.0 % |
| 2019 | 17.0 % |
| 2020 | 10.0 % |
| 2021 | 14.0 % |
| 2022 | 8.0 % |
| 2023 | -5.0 % |
| 2024 | -3.0 % |
| 2025 | 6.0 % |
| 2026 | -1.0 % |
Measured over longer periods, average annual change stands at 8.4 % over fifteen years and 7.2 % over ten years.
| Period | Avg. sale price per sqm |
|---|---|
| 2012 | €1,700 per sqm |
| 2013 | €1,890 per sqm |
| 2014 | €2,060 per sqm |
| 2015 | €2,320 per sqm |
| 2016 | €2,620 per sqm |
| 2017 | €2,980 per sqm |
| 2018 | €3,390 per sqm |
| 2019 | €3,950 per sqm |
| 2020 | €4,350 per sqm |
| 2021 | €4,980 per sqm |
| 2022 | €5,360 per sqm |
| 2023 | €5,110 per sqm |
| 2024 | €4,980 per sqm |
| 2025 | €5,290 per sqm |
| 2026 | €5,230 per sqm |
Prices by location
The highest prices per square metre are notarised in Mitte (€6,620 per sqm), Friedrichshain-Kreuzberg (€5,770 per sqm) and Charlottenburg-Wilmersdorf (€5,750 per sqm). The lowest are in Spandau (€3,380 per sqm), Reinickendorf (€3,700 per sqm) and Marzahn-Hellersdorf (€3,890 per sqm). The full ranking of all twelve boroughs is shown in the table.
Within individual boroughs, values lie further apart than between some boroughs. In the district of Mitte the price per square metre is €8,650 per sqm, in the district of Wedding it is €4,110 per sqm. Both belong to the borough of Mitte.
Supply and notarisations
The gap between asking price and transaction price stands at 8 % or €400 per sqm.
| Period | Avg. price difference |
|---|---|
| 2012 | 25 % |
| 2013 | 23 % |
| 2014 | 25 % |
| 2015 | 29 % |
| 2016 | 21 % |
| 2017 | 20 % |
| 2018 | 18 % |
| 2019 | 13 % |
| 2020 | 12 % |
| 2021 | 6 % |
| 2022 | 7 % |
| 2023 | 10 % |
| 2024 | 13 % |
| 2025 | 9 % |
| 2026 | 8 % |
As at the data cut-off for this edition, 6,768 notarisations are recorded. For 2025 the series shows 12,514. The current-year figure is incomplete because notarisations are reported with a lag.
| Period | Number of sales |
|---|---|
| 2012 | 14,310 |
| 2013 | 14,098 |
| 2014 | 10,980 |
| 2015 | 12,669 |
| 2016 | 12,242 |
| 2017 | 11,042 |
| 2018 | 9,901 |
| 2019 | 11,281 |
| 2020 | 11,133 |
| 2021 | 13,705 |
| 2022 | 10,750 |
| 2023 | 9,502 |
| 2024 | 11,364 |
| 2025 | 12,514 |
| 2026 | 6,768 |
On the supply side, 37,107 listings are recorded, against 28,928 for 2025.
| Period | Number of purchase listings |
|---|---|
| 2012 | 25,308 |
| 2013 | 29,606 |
| 2014 | 25,120 |
| 2015 | 27,630 |
| 2016 | 21,840 |
| 2017 | 23,131 |
| 2018 | 23,198 |
| 2019 | 21,559 |
| 2020 | 22,559 |
| 2021 | 19,779 |
| 2022 | 17,165 |
| 2023 | 23,429 |
| 2024 | 31,044 |
| 2025 | 28,928 |
| 2026 | 37,107 |
Other factors in pricing
Alongside location, availability, construction period, condition and size all affect price. The average living area of notarised resale apartments is 70 sqm; in 2010 it was 74 sqm. The average transaction price is €374,800, against €109,200 in 2010.
By availability, sales divide between vacant and occupied units and tenant purchases.
Sales are distributed unevenly across construction periods. The largest share is accounted for by apartments built up to 1918, followed by the 1950 to 1964 period.
The table below describes the characteristics of each construction period.
| Construction period | Characteristics |
|---|---|
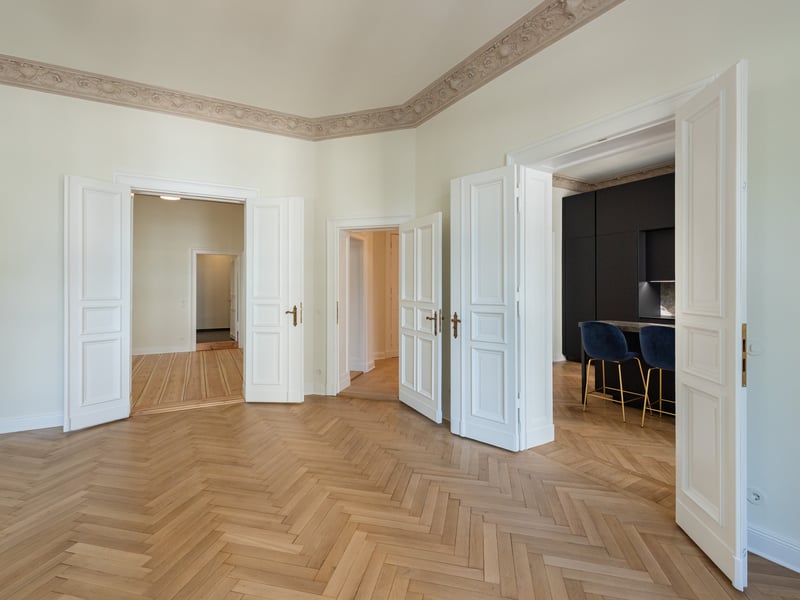
| Up to 1918 | Berlin Altbau with high ceilings, often stucco, solid construction. Predominantly in inner-city locations. |
| 1919–1949 | Interwar and early post-war buildings, more compact layouts, lower ceilings. Condition and quality vary. |
| 1950–1964 | Post-war buildings with basic substance and pragmatic layouts. Weak on energy efficiency. |
| 1965–1972 | Functional layouts of post-war modernism, with different construction methods in East and West. Weak on energy efficiency. |
| 1973–1990 | Late GDR-era stock in the East using industrial construction, occasional higher-quality projects in the West. Heterogeneous quality. |
| 1991–2002 | Post-reunification stock, often standardised developer projects. Mid-range build quality. |
| 2003–2013 | Modern layouts, higher energy standards, established developments. |
| From 2014 | Current new-build standard with high energy efficiency. Highest prices in the segment. |
New development market
New developments are notarised at an average of €8,440 per sqm. Year on year, the change is €240 per sqm or 3.0 %. Over ten years, the change is 106.0 %, an average annual change of 7.5 %.
| Period | Avg. sale price per sqm |
|---|---|
| 2012 | €2,890 per sqm |
| 2013 | €3,060 per sqm |
| 2014 | €3,350 per sqm |
| 2015 | €3,810 per sqm |
| 2016 | €4,100 per sqm |
| 2017 | €4,540 per sqm |
| 2018 | €4,840 per sqm |
| 2019 | €6,030 per sqm |
| 2020 | €6,500 per sqm |
| 2021 | €7,440 per sqm |
| 2022 | €7,910 per sqm |
| 2023 | €7,840 per sqm |
| 2024 | €7,980 per sqm |
| 2025 | €8,200 per sqm |
| 2026 | €8,440 per sqm |
As at the data cut-off for this edition, 833 notarisations are recorded. For 2025 the series shows 1,428.
| Period | Number of sales |
|---|---|
| 2012 | 4,721 |
| 2013 | 5,224 |
| 2014 | 4,682 |
| 2015 | 7,099 |
| 2016 | 7,270 |
| 2017 | 6,196 |
| 2018 | 4,985 |
| 2019 | 3,501 |
| 2020 | 3,088 |
| 2021 | 3,580 |
| 2022 | 2,102 |
| 2023 | 1,239 |
| 2024 | 1,460 |
| 2025 | 1,428 |
| 2026 | 833 |
The average living area of notarised new developments is 57 sqm. In 2015 it was 82 sqm.
Rental market
The average asking rent for resale apartments is €18 per sqm net cold. For new developments it is €22 per sqm. Year on year, the change for new developments is -€1.00 per sqm.
In 2015 the asking rent in the resale segment was €9 per sqm, in 2020 €11 per sqm.
Asking rents include furnished and fixed-term lettings. Their share of total supply cannot be determined from listing data.
| Period | Avg. rental asking price per sqm |
|---|---|
| 2017 | €10 per sqm |
| 2018 | €11 per sqm |
| 2019 | €11 per sqm |
| 2020 | €11 per sqm |
| 2021 | €12 per sqm |
| 2022 | €13 per sqm |
| 2023 | €15 per sqm |
| 2024 | €17 per sqm |
| 2025 | €18 per sqm |
| 2026 | €18 per sqm |
For new developments the series follows its own path.
| Period | Avg. rental asking price per sqm |
|---|---|
| 2017 | €12 per sqm |
| 2018 | €14 per sqm |
| 2019 | €15 per sqm |
| 2020 | €17 per sqm |
| 2021 | €19 per sqm |
| 2022 | €22 per sqm |
| 2023 | €27 per sqm |
| 2024 | €26 per sqm |
| 2025 | €23 per sqm |
| 2026 | €22 per sqm |
Asking rents relate to new lettings. The 2022 census, by contrast, captures the entire rent level across the existing stock and reports an average net cold rent of €7.8 per sqm. In all twelve boroughs, asking rents lie above census rents. The range by borough is shown in the table.
Social housing
Berlin's building authorities reported 13,754 approved apartments for 2025 according to the final figures of the Berlin-Brandenburg Statistics Office, after 9,772 in 2024. Within social housing, the Senate granted approval for 5,175 apartments. Most subsidised apartments are aimed at middle incomes, with entry rents of €11.50 per square metre. At the end of 2023, Berlin counted just under 100,000 social housing units, against 105,000 a year earlier. Around 5,000 apartments leave their subsidy commitment each year.
Housing demand
For the period from 2022 to 2040, the 2024 Urban Development Plan Housing (Stadtentwicklungsplan Wohnen) puts housing demand at 272,000 apartments. The figure comprises additional demographic demand of 85,000 units from in-migration, relief demand of 137,000 apartments to establish a fluctuation reserve of around three percent, and a land reserve of 50,000 units. The plan makes no statements on future rent or price developments. In inner-city locations, additional housing arises predominantly through densification and conversion, in new quarters on the urban fringe through new construction.
Outlook
The citywide year-on-year change of -1.0 % is an average across opposing movements. Through the third quarter of 2026, little is moving in the large districts. The established names, Friedrichshain, Kreuzberg, Charlottenburg, Wilmersdorf and Neukölln, each lie between −1 % and +3 %. The larger swings mostly come from districts with low transaction counts. The one exception is Halensee at 17.0 % on 82 notarisations.
No citywide trend can be read from this. The subdued development may also reflect the very open outcome of the forthcoming election to the House of Representatives. Whether home ownership and letting are recognised as a social good will depend on the coalition that forms at state level, and on the composition of the twelve borough councils.
On the interest rate side, the ECB Governing Council raised all three key rates by 0.25 percentage points on 10 September 2026, following a first step in June 2026. The deposit facility rate stands at 2.50 percent, the main refinancing rate at 2.65 percent and the marginal lending facility at 2.90 percent. Brokers reported conditions of around 4.2 percent for ten-year loans on 10 September 2026.
Berlin continues to enjoy the confidence of international buyers, who are returning to the market. These investors view regulation and sentiment with more distance than landlords involved and invested in Berlin can.
How quickly Berlin's property market returns to strength depends less on the quantitative conditions. The vacancy rate still stands at around 2.0 percent, and net additions to the housing stock remain too low to replenish it to the point where pressure escapes the rental market. In 2024 the net housing balance was 15,362 apartments.
That Berlin continues to hold up is shown by the CAGR, the average annual change in the resale market, which stands at 7.2 % despite the corrections of recent years.
Methodology
Data cut-off for this edition: transaction data as at 09.09.2026, listing data as at 31.08.2026. Current-year figures are part-year and not comparable with completed years.
Asking prices and asking rents are reported as medians, transaction prices as arithmetic means. The price gap and the comparison with census rents therefore set differently calculated measures of central tendency against one another.
Data sources: Gutachterausschuss für Grundstückswerte in Berlin for transaction data and IMV Immobilien-Marktdaten-Vertriebs GmbH for listing data. Own calculation, aggregation and presentation across Berlin's spatial levels of borough, district and neighbourhood. The figures shown are based on a model-based analysis and do not replace official statistics. Deviations cannot be ruled out.
Subscribe to our newsletter
Receive the latest market analyses and insights directly in your inbox every month.
- Monthly insights
- No spam
Apartment Buildings
Purchase prices, yields, and market trends for residential and commercial buildings in Berlin.
Macroeconomics
Key interest rates, inflation, and economic conditions for the real estate market.
Was this page helpful?
Your feedback helps us improve this page.